Understanding the 2026 COLA Impact on Your Retirement Benefits
As we navigate the complexities of economic forecasts and personal finance, one topic consistently captures the attention of retirees and those nearing retirement: the Cost-of-Living Adjustment (COLA). Specifically, the 2026 COLA Impact is a critical point of discussion, promising to shape the financial landscape for millions of Social Security beneficiaries. Understanding how COLA works, its historical context, and what projections for 2026 might mean for your retirement benefits is not just important; it’s essential for sound financial planning.
The COLA is more than just a number; it’s a vital mechanism designed to protect the purchasing power of Social Security and other government benefits against the erosive effects of inflation. Without these annual adjustments, the fixed income of retirees would steadily lose value, making it increasingly difficult to cover basic living expenses. Therefore, grasping the potential 2026 COLA Impact is paramount for ensuring financial stability in your golden years.
This comprehensive guide will delve deep into the intricacies of COLA, explore the factors influencing its calculation, provide insights into potential 2026 projections, and offer strategies to help you prepare for and maximize the benefits of these adjustments. Whether you are already receiving benefits or planning for retirement, this information will empower you to make informed decisions about your financial future.
Anúncios
What is COLA and Why is it Important?
COLA, or Cost-of-Living Adjustment, is an annual increase in Social Security and Supplemental Security Income (SSI) benefits. Its primary purpose is to counteract inflation, ensuring that the purchasing power of beneficiaries does not diminish over time. Essentially, as the cost of goods and services rises, COLA aims to adjust benefit payments upwards to match these increases, allowing retirees and other beneficiaries to maintain their standard of living.
The importance of COLA cannot be overstated. For many seniors, Social Security represents a significant, if not primary, source of income. Without regular adjustments, rising costs for essentials like food, housing, healthcare, and utilities would quickly outpace their fixed benefits, leading to financial hardship. The 2026 COLA Impact, like those before it, will be a direct reflection of economic conditions, particularly inflation, in the preceding year.
Anúncios
Historically, COLA has been a cornerstone of retirement security. It provides a degree of predictability and stability in an otherwise unpredictable economic environment. Understanding its function is the first step in appreciating its significance and preparing for its future implications, especially the anticipated 2026 COLA Impact.
How is COLA Calculated? The CPI-W Connection
The calculation of COLA is not arbitrary; it follows a specific formula mandated by law. Since 1975, Social Security COLAs have been based on the percentage increase in the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). The CPI-W is a measure of the average change over time in the prices paid by urban wage earners and clerical workers for a market basket of consumer goods and services.
Here’s a breakdown of the calculation process:
- Measuring Inflation: The Social Security Administration (SSA) compares the average CPI-W for the third quarter (July, August, and September) of the current year with the average CPI-W for the third quarter of the last year in which a COLA was enacted.
- Percentage Increase: The percentage increase between these two periods determines the COLA. For example, to determine the 2026 COLA, the SSA will compare the average CPI-W for the third quarter of 2025 with the average CPI-W for the third quarter of 2024 (assuming a COLA was enacted for 2025).
- No Increase if No Inflation: If there is no increase, or if prices decrease, there is no COLA. This means benefits would remain the same, although they would not decrease.
- Rounding: The resulting percentage increase is then rounded to the nearest one-tenth of one percent.
It’s important to note that the CPI-W is specifically designed for urban wage earners and clerical workers, which some argue may not fully represent the spending patterns of seniors. Critics often point to the fact that healthcare costs, a significant expenditure for many retirees, tend to rise faster than the overall CPI-W, potentially leading to a COLA that doesn’t fully cover their specific cost increases. This debate often surfaces when discussing the adequacy of the COLA, and it will undoubtedly be a factor in the discussion around the 2026 COLA Impact.
Historical Context: COLA Trends and Economic Factors
Looking back at historical COLA adjustments provides valuable context for understanding the potential 2026 COLA Impact. Over the decades, COLA percentages have varied significantly, reflecting different economic environments. Periods of high inflation, such as the late 1970s and early 1980s, saw double-digit COLA increases. Conversely, periods of low inflation have resulted in very small or even zero COLAs.
- High Inflation Eras: In the late 1970s and early 1980s, COLAs were substantial, with some years seeing increases over 10%. This was a direct response to rampant inflation during those periods.
- Moderate Increases: The 1990s and early 2000s generally saw moderate COLA increases, typically in the 2-4% range, reflecting more stable economic growth and inflation.
- Low or Zero COLAs: In more recent history, particularly during and after the 2008 financial crisis, there have been years with very low or even zero COLA increases (e.g., 2010, 2011, 2016). These periods were characterized by low inflation or even deflationary pressures.
- Recent Spikes: More recently, especially in the wake of the COVID-19 pandemic and subsequent supply chain disruptions and increased demand, inflation has seen a resurgence, leading to some of the largest COLA increases in decades for 2022 and 2023.
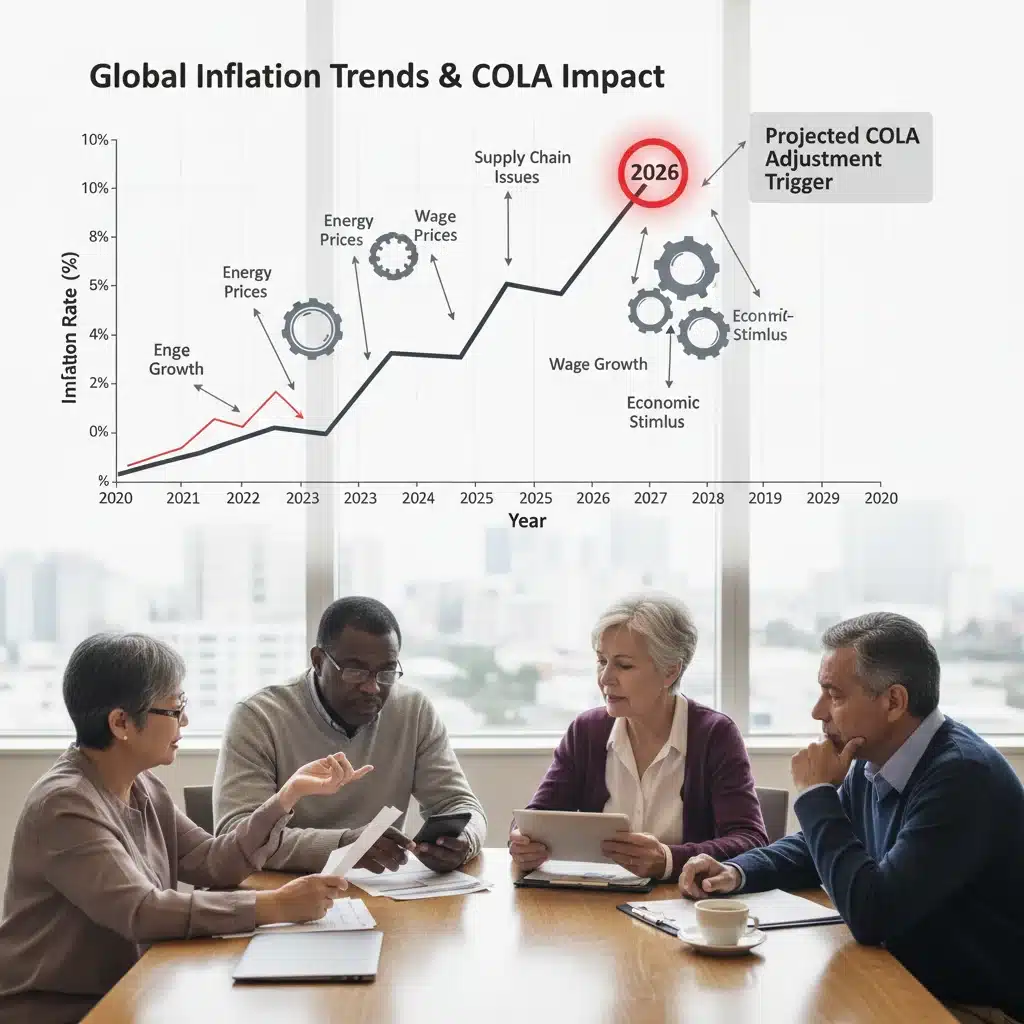
Understanding these trends helps us appreciate that the 2026 COLA Impact will not occur in a vacuum. It will be a direct consequence of the economic conditions prevailing in 2024 and 2025, particularly inflation rates as measured by the CPI-W. Factors such as global economic stability, energy prices, supply chain resilience, and consumer demand will all play a role in shaping the inflation landscape and, by extension, the 2026 COLA.
Projections for the 2026 COLA Impact: What to Expect
While it’s impossible to predict the exact 2026 COLA Impact with certainty, we can look at current economic forecasts and expert analyses to form reasonable expectations. Projections are typically based on anticipated inflation rates, particularly the CPI-W. Several economic indicators and expert opinions come into play when estimating future COLAs.
Key Factors Influencing 2026 COLA Projections:
- Inflation Trends: The most significant factor is the trajectory of inflation. If inflation remains elevated or continues to rise in 2024 and 2025, the 2026 COLA is likely to be higher. Conversely, if inflationary pressures ease, the COLA will be lower.
- Federal Reserve Policy: The Federal Reserve’s monetary policy, including interest rate decisions, directly influences inflation. Aggressive rate hikes aim to cool the economy and reduce inflation, which could lead to smaller COLAs.
- Energy Prices: Fluctuations in oil and gas prices have a substantial impact on the CPI-W, as they affect transportation costs and the price of many goods.
- Supply Chain Stability: Ongoing global supply chain issues can lead to higher prices for goods, contributing to inflation. Improved stability could help mitigate price increases.
- Wage Growth: Strong wage growth can sometimes fuel inflation, as businesses pass on higher labor costs to consumers.
- Geopolitical Events: International conflicts or significant political shifts can disrupt global markets and supply chains, leading to unpredictable inflationary pressures.
Financial analysts and organizations often release their own COLA projections. While these are estimates and subject to change, they provide valuable insights. For instance, if current inflation trends suggest a cooling economy but still above-target inflation, we might anticipate a moderate 2026 COLA Impact, perhaps in the 2-4% range. However, significant economic shifts could push this number higher or lower.
It’s crucial for beneficiaries and those planning for retirement to monitor these economic indicators and projections from reputable sources. This proactive approach allows for better financial planning and adjustment of expectations regarding the 2026 COLA Impact.
How the 2026 COLA Impact Affects Your Retirement Planning
The 2026 COLA Impact will have direct implications for your retirement benefits and overall financial planning. Understanding these effects allows you to adjust your strategies accordingly.
Direct Impact on Benefits:
- Increased Income: A positive COLA means an increase in your monthly Social Security benefits. This directly boosts your income, helping you keep pace with rising living costs.
- Maintaining Purchasing Power: The primary goal of COLA is to preserve your purchasing power. A robust COLA helps ensure that your benefits can still cover the same amount of goods and services as they did previously.
Broader Financial Implications:
- Healthcare Costs: While COLA adjusts benefits, Medicare Part B premiums are often deducted directly from Social Security checks. If Part B premiums rise significantly, a substantial portion of your COLA increase might be absorbed by these higher costs, potentially diminishing the net benefit. This is a critical consideration when evaluating the true 2026 COLA Impact.
- Taxation of Benefits: Depending on your total income, a portion of your Social Security benefits may be subject to federal income tax. An increase in benefits due to COLA could, in some cases, push you into a higher income bracket, leading to a greater percentage of your benefits being taxed. It’s essential to understand the Social Security taxation rules.
- Means-Tested Programs: For individuals receiving benefits from other means-tested government programs, an increase in Social Security income due to COLA could potentially affect their eligibility or benefit levels for those programs. This is a less common but important consideration for some beneficiaries.
- Inflation Expectations: The COLA itself is a lagging indicator, based on past inflation. However, the expectation of a certain COLA can influence broader economic behavior and personal financial decisions.
For effective retirement planning, it’s advisable to not solely rely on COLA increases to cover all your rising expenses. While COLA is a valuable safeguard, incorporating other savings, investments, and diverse income streams into your retirement plan provides a more robust financial foundation. The 2026 COLA Impact should be viewed as one piece of a larger financial puzzle.
Strategies to Prepare for the 2026 COLA and Beyond
Proactive planning is key to navigating the financial landscape of retirement, especially concerning adjustments like the 2026 COLA Impact. Here are some strategies to help you prepare:
1. Monitor Economic Indicators:
Stay informed about inflation rates, particularly the CPI-W, and general economic forecasts. Websites of government agencies like the Bureau of Labor Statistics (BLS) and reputable financial news outlets are excellent resources. Understanding the economic climate will give you an early indication of potential COLA changes.
2. Review Your Budget Regularly:
Periodically assess your household budget to understand where your money is going. Identify areas where you might be able to cut back if necessary, or where expenses are increasing faster than your COLA adjustments. This is particularly important for discretionary spending.
3. Account for Healthcare Costs:
Healthcare is a significant and often unpredictable expense in retirement. Plan for potential increases in Medicare premiums, deductibles, and out-of-pocket costs. Explore options like Medicare Advantage plans or Medigap policies to manage these expenses. Remember that a portion of your 2026 COLA Impact might be offset by rising healthcare costs.
4. Diversify Income Streams:
Relying solely on Social Security can be risky. Consider diversifying your retirement income through personal savings, investments (e.g., IRAs, 401(k)s, annuities), part-time work, or other assets. This diversification provides a buffer against potentially low COLA years.
5. Understand Tax Implications:
Consult with a tax professional to understand how COLA increases might affect the taxation of your Social Security benefits and your overall tax liability. Strategic tax planning can help you keep more of your hard-earned benefits.
6. Delay Social Security (If Possible):
For those still able to choose when to claim Social Security, delaying benefits beyond your Full Retirement Age (FRA) can result in significantly higher monthly payments. These higher payments will then also be subject to COLA increases, amplifying the 2026 COLA Impact on a larger base amount.
7. Consider Long-Term Care:
Long-term care can be a substantial expense not fully covered by Medicare. Explore options like long-term care insurance or self-funding strategies to protect your assets and ensure you can afford necessary care without depleting your retirement savings, regardless of the COLA.
The Broader Economic Picture and Future COLAs
The 2026 COLA Impact will not be an isolated event but rather a reflection of the ongoing economic narrative. The global economy is constantly evolving, influenced by technological advancements, geopolitical shifts, demographic changes, and environmental factors. Each of these elements can contribute to inflationary or deflationary pressures, directly affecting future COLA calculations.
Factors to Watch Beyond 2026:
- Demographics: The aging population in many developed countries means a growing number of Social Security beneficiaries relative to the number of workers contributing. This demographic shift can put pressure on the Social Security system’s finances, potentially leading to future policy discussions that could indirectly affect COLAs.
- Technological Innovation: Advancements in technology can impact productivity and costs. While some innovations might reduce prices (e.g., automation), others might create new demands and inflationary pressures.
- Climate Change and Energy Transition: The transition to green energy and the impact of climate change on agriculture and infrastructure can lead to significant cost fluctuations, influencing the CPI-W.
- Global Trade Dynamics: Changes in international trade agreements, tariffs, and global supply chains will continue to play a crucial role in the prices of imported goods and, consequently, domestic inflation.
Understanding these broader trends helps beneficiaries and policymakers alike to anticipate long-term challenges and opportunities. While the immediate focus is on the 2026 COLA Impact, a holistic view of the economic future is essential for sustainable retirement planning.
Conclusion: Empowering Your Retirement with COLA Knowledge
The 2026 COLA Impact stands as a significant event for millions of Americans relying on Social Security benefits. It underscores the critical role of Cost-of-Living Adjustments in safeguarding the purchasing power of retirees and ensuring their financial well-being amidst an ever-changing economic landscape. By understanding how COLA is calculated, its historical performance, and the factors influencing future adjustments, you can proactively plan and adapt your financial strategies.
Remember, while COLA is a powerful tool against inflation, it is just one component of a comprehensive retirement plan. Integrating knowledge about COLA with diligent budgeting, diversified income streams, and informed healthcare planning will provide the most robust foundation for a secure and comfortable retirement. Stay informed, plan wisely, and empower yourself to face the future with confidence, knowing how the 2026 COLA Impact and subsequent adjustments will play a role in your financial journey.
Taking the time now to understand these dynamics will not only alleviate potential anxieties but will also position you to make the most of your retirement benefits, ensuring that your golden years are truly golden.